By Yuvraj Grover | Co-Founder, Aspyra Partners
It's income tax time again: time to gather up those receipts, get out those tax forms, sharpen up that pencil, and stab yourself in the aorta. --Dave Berry
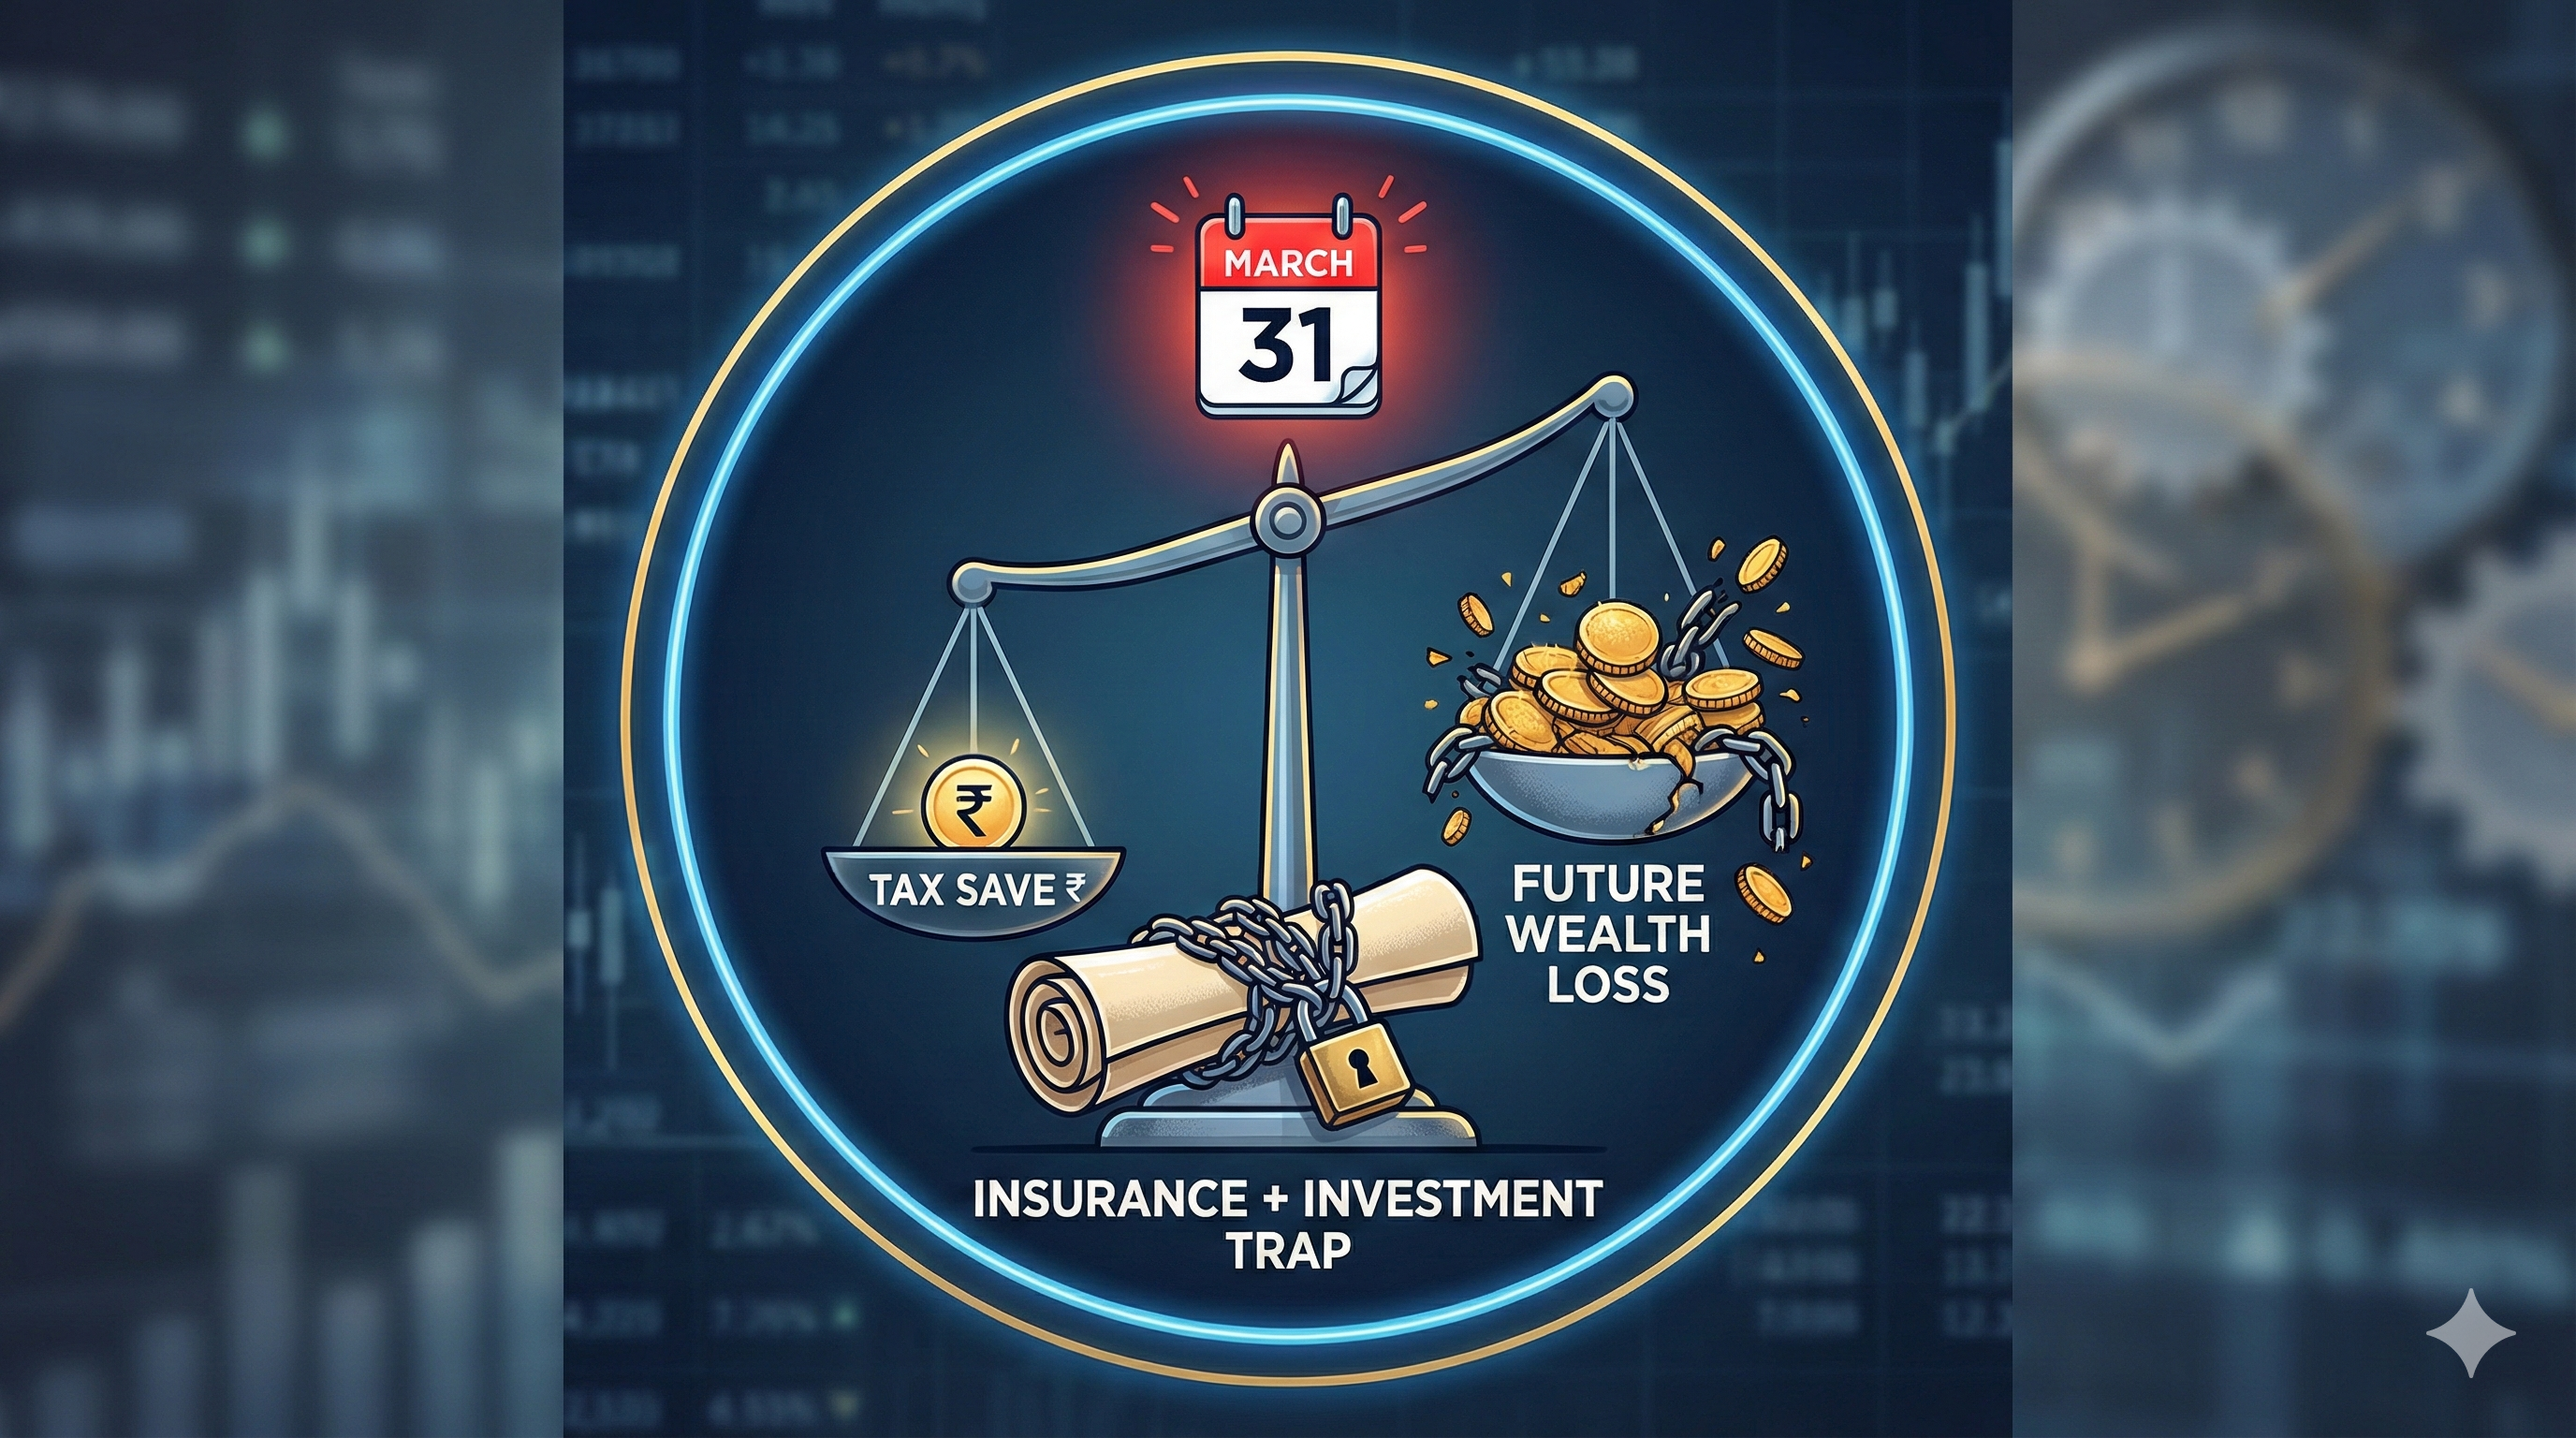
Every year, between late January and March, a predictable frenzy grips the Indian retail investor. The HR department sends an ultimatum for tax-saving investment proofs. Panic ensues. To save ₹15,000 or ₹30,000 in income tax, otherwise rational individuals rush to buy 20-year traditional insurance policies, lock their cash in 5-year Fixed Deposits, or scramble for the nearest ELSS fund without analyzing their asset allocation.
We call this the "March Panic." At Aspyra Partners, our fundamental strength lies in understanding the retail mindset. We know that nobody likes paying taxes. However, allowing the fear of taxation to dictate your investment strategy is a guaranteed way to destroy long-term compounding. Tax planning should be a boring byproduct of wealth creation, not the driver of it.
Here is the raw math behind why your current tax-saving formula might be a massive wealth-destruction trap.
The 'Insurance + Investment' Package Trap
The most common casualty of the March Panic is the purchase of bundled financial products—specifically, traditional endowment plans, money-back policies, and poorly structured ULIPs.
The pitch is alluring: "Get life cover, save tax under Section 80C, and get a guaranteed maturity amount." It sounds like a win-win, but it is mathematically a no-win situation for the average investor. Insurance and investments serve two completely opposite functions. Insurance is a cost designed to mitigate risk (defense). Investing is the deployment of capital to beat inflation and compound wealth (offense).
When you bundle them, you get a highly inefficient product. After accounting for mortality charges, administrative fees, and agent commissions, the internal rate of return (IRR) on traditional policies usually hovers around 5% to 6%.
[Image of compounding vs simple interest graph]
The Math of Opportunity Cost: Imagine you invest ₹1,50,000 annually in a traditional plan for 20 years to save tax. At a 6% return, your corpus at maturity is roughly ₹55 Lakhs.
Now, imagine you separate the two. You buy a pure Term Insurance cover for ₹10,000 a year (vastly higher coverage) and invest the remaining ₹1,40,000 systematically into a rigorously constructed, data-driven mutual fund portfolio. Assuming a conservative 12% equity return over 20 years, your corpus grows to approximately ₹1.1 Crores.
By trying to save ₹45,000 in tax today, you forfeited ₹55 Lakhs in future wealth.
The Regime Math: Do You Actually Need to Save Tax?
Before you rush to lock away your liquidity, ask yourself a fundamental question: Do I even need to make these investments to save tax anymore?
The Union Budget has aggressively pushed the New Tax Regime, which changes the math entirely for the financial year. Under the new regime, the standard deduction for salaried employees was expanded, and an increased rebate means that a significant portion of income can be completely tax-free.
Here is the catch: The New Tax Regime does not allow deductions under Section 80C.
We see investors blindly buying tax-saving FDs or insurance policies out of sheer habit, locking up their liquidity for a tax benefit they aren't even eligible for under the new system. Even if you are in a higher bracket, the break-even math shows you would need massive combined deductions under the Old Regime just to beat the low flat rates of the New Regime.
For many investors, the optimal strategy is simple: opt for the New Regime, enjoy the lower tax slab, and keep 100% of your capital liquid to invest in high-alpha growth assets.
The Exception: The NPS 14% Corporate Cheat Code
While Section 80C is essentially dead in the New Regime, one powerful deduction survived and thrived: Section 80CCD(2).
This section covers the employer's contribution to your National Pension System (NPS) account. Under the New Tax Regime, employers can contribute up to 14% of your Basic Salary + DA into your NPS, and this entire amount is tax-deductible. The rules have now harmonized, bringing private employees on par with government workers at 14%.
Furthermore, the PFRDA (Pension Fund Regulatory and Development Authority) introduced massive rule relaxations that make NPS highly attractive:
- Lower Annuity Burden: Previously, you were forced to use 40% of your retirement corpus to buy an annuity (a pension product). Now, non-government subscribers can withdraw up to 80% as a lump sum at retirement, with only 20% requiring annuitization.
- Small Corpus Freedom: If your total corpus at retirement is ₹8 lakh or less, you can now withdraw 100% of it immediately.
If you are in the highest tax bracket, routing part of your salary through your employer into NPS via 80CCD(2) is mathematically one of the most efficient wealth-building strategies available today.
When to Skip NPS and Just Pay the Tax
While NPS is tax-efficient, it is not a silver bullet. The funds are locked until you turn 60, save for a few highly specific partial withdrawal allowances.
If you are a 30-year-old high-earner with aggressive ambitions—perhaps aiming for early retirement at 45, or planning to start a business—NPS restricts your capital flexibility for three decades.
In personal finance, liquidity commands a premium. Sometimes, the most logical decision is to simply pay the 30% tax slab, take your cash, and deploy it into a liquid, well-engineered equity mutual fund portfolio. The ability to dynamically shift allocations, rebalance critically, and exit when your personal goals demand it is often worth far more than the upfront tax saved.
The Verdict
Do not let the March Panic dictate your financial future. Separate your insurance from your investments. Run a break-even analysis on the New Tax Regime before buying another Section 80C product. And above all, never prioritize a minor tax deduction over the compounding power of a fundamentally strong, liquid portfolio.
Disclaimer: The content provided in this article is for educational and informational purposes only and reflects the personal views of the authors at Aspyra Partners. It does not constitute formal legal, financial, or tax advice. Tax laws are subject to change, and individual financial situations vary. Please consult with a qualified Chartered Accountant (CA) or financial advisor before making any tax-planning or investment decisions.